
- India,
- 05-Nov-2026 02:03 PM IST


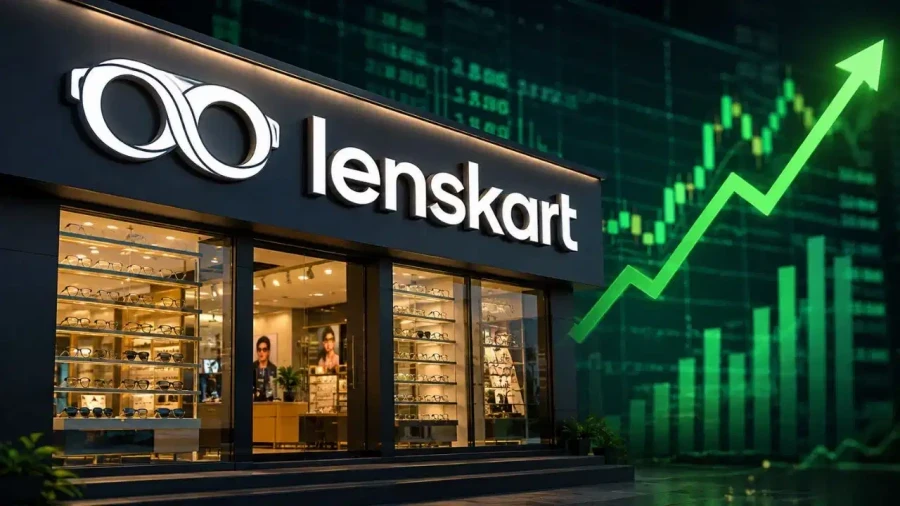
Shares of the renowned eyewear company Lenskart Solutions Limited witnessed massive buying interest on November 5. During the trading session on the BSE, the company's stock surged by 11 percent compared to its previous closing price. 40 rupees. 27 lakh crore rupees mark. This market enthusiasm follows the company's impressive quarterly results released just a day earlier.
Strong performance on the earnings front
Lenskart released its quarterly and half-yearly results a day prior. In the July to September 2026 quarter, the company delivered an exceptional performance. 45 crore rupees. In the same quarter last year, the company had earned a profit of 113 crore rupees. 2 percent.
A significant jump was also recorded in the company's total revenue from operations. 03 crore rupees. 14 crore rupees. Regarding the operating profit or EBITDA, it jumped by 50 percent to reach 621 crore rupees, compared to 414 crore rupees a year ago. The company's EBITDA margin also increased from 20 percent last year to 22 percent.
Business expansion into 61 new cities
Along with the rise in profits, Lenskart has rapidly expanded its business operations. During the July-September quarter, the company opened a total of 165 new stores. With this, the total number of active stores has increased to 3,624. Focusing specifically on India, the company launched 143 new stores. Through this expansion, Lenskart has established its presence in 61 new cities across the country.
Brokerage firms raise share price targets
Following the strong September quarter results, major brokerage firms have expressed increased confidence in Lenskart shares. Brokerage house Nomura described the company's performance as better than expected and maintained a Buy rating on the stock. Nomura has set a target price of 888 rupees per share. On the other hand, HSBC upgraded the stock rating to Buy and increased the target price to 790 rupees. The brokerage stated that it has revised its estimates regarding margin expansion in India. On top of that, the company now views its international business as a significant growth opportunity compared to before. Among other brokerage firms, Jefferies maintained a Buy rating with a target of 780 rupees. Jefferies believes that the combination of strong growth and margin expansion sustains the company's development momentum. Despite foreign exchange pressures, the improvement in the company's margins is moving in the right direction. Meanwhile, CLSA has given the stock an Outperform rating with a target price of 773 rupees.