
- India,
- 08-Oct-2026 01:11 PM IST


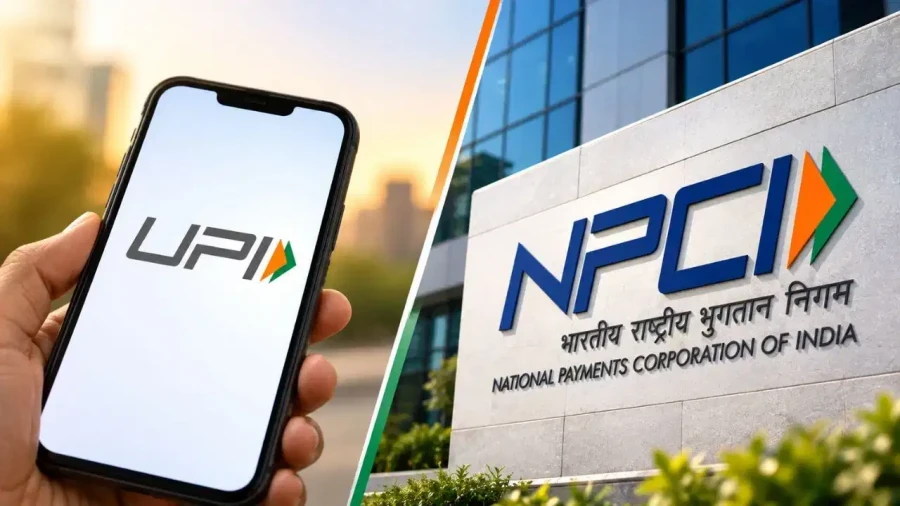
There is significant news regarding the new charges on digital payments as the National Payments Corporation of India (NPCI) might postpone the implementation of the Merchant Discount Rate (MDR) on UPI transactions. Originally scheduled to take effect from October 15, 2026, the new fee structure is now expected to be deferred until January 2027. This potential move comes as a major relief for traders and merchants who have been seeking a reprieve amidst rising inflation and the approaching festive season. With less than a week remaining before the initial deadline, merchant associations, fintech companies, and payment service providers have collectively urged the NPCI to push back the date. Sources indicate that the NPCI could announce a final decision within the next two days, following ongoing discussions with the Ministry of Finance.
Demands from the Industry Amid Festive Season
The industry has voiced concerns that they aren't yet fully prepared to adopt this new system. The primary reasons cited for this lack of readiness include the varying MDR rates, differing policies, and a general sense of confusion regarding their implementation. As the country prepares for major shopping events like Diwali and other significant festivals, payment industry bodies have argued that the decision should be delayed until the festive period concludes. The government also shares concerns that imposing MDR during peak festive sales could increase the cost of doing business. With inflation already impacting the market and putting pressure on the purchasing power of the common public, any additional burden on merchants might be passed on to consumers, potentially dampening the festive shopping spirit.
Understanding the New MDR Rules
MDR is the fee that merchants pay to banks for accepting digital payments. 4 percent, or 40 basis points, for transactions exceeding 2000 rupees. If this rule is implemented, a shopkeeper or merchant would have to pay 8 rupees for a UPI payment of 2000 rupees. Similarly, a transaction of 10000 rupees would attract a fee of 40 rupees. Although the NPCI had initially decided to enforce this from October 15, 2026, the industry now maintains that a lack of technical and policy clarity makes immediate implementation difficult.
UPI Complexity Compared to Card Payments
The structure of UPI appears Notably more complex than that of card payments. Generally, merchants who accept card payments have specific category codes, which card networks use to process and verify transactions. These rates are largely uniform across card networks. In contrast, UPI has different rates set for various services. For instance, utility bills like electricity and water, loan repayments, and capital market investments have distinct rates. Interestingly, many of these payments aren't even permitted via cards; for example, the RBI doesn't allow the use of credit cards for loan repayments or stock market investments. Before the advent of UPI, these transactions were handled through Net Banking, IMPS, NEFT, or RTGS, which involved charges but didn't follow the card-like MDR system where banks charged both the sender and the receiver.
Confusion in Loan and Stock Market Transactions
Capital market firms have expressed their concerns to the market regulator. Broking companies argue that when a customer transfers money into their trading account, it's akin to a direct Person-to-Person (P2P) transfer. Since broking firms don't earn direct income from these funds, they believe imposing MDR is unjustified. Another major complication involves loan installments. According to NPCI guidelines, a flat fee of 5 rupees is supposed to apply to loan payments made via auto-pay mandates. However, many small-loan customers often lack the required balance, leading to auto-debit failures. 4 percent MDR charge. While the NPCI has clarified that all loan payments should only attract a 5 rupee fee, banks and payment aggregators currently lack the technical means to distinguish between general financial transactions and loan repayments. The industry has requested more time from the NPCI to rectify these technical flaws.