
- India,
- 25-Sep-2026 05:26 PM IST


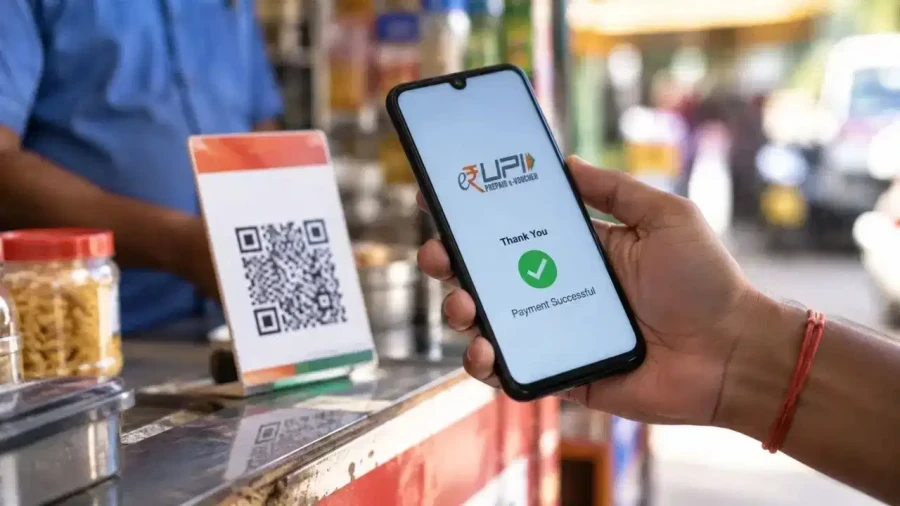
The landscape of digital payments in India is set for a significant transformation as new regulations regarding Unified Payments Interface (UPI) transactions are scheduled to take effect from October 15 2026. These changes introduce a Merchant Discount Rate (MDR) on specific types of Person-to-Merchant (P2M) transactions, marking a shift in how digital payments are processed and monetized. 4 percent MDR will be applicable to certain P2M UPI transactions. For high-value transactions exceeding 75000, the MDR has been capped at a maximum of 300 per transaction. However, the policy provides relief for smaller transactions, as P2M payments up to 2000 and all Person-to-Person (P2P) transactions will remain outside the ambit of this MDR.
The Financial Impact on a 6000 Rupee Transaction
To understand the practical implications of these rules, consider a scenario where a customer needs to pay a merchant a total of 6000.4 percent. This cost is borne by the merchant as a fee for accepting digital payments. The introduction of this rate has led to discussions about whether customers or merchants might attempt to split larger bills into smaller segments to stay below the 2000 threshold where the MDR is zero.
The Strategy of Splitting Payments
A common question arising from this new structure is whether splitting a 6000 bill into three separate transactions of 2000 each can effectively bypass the MDR. According to the proposed framework, the calculation of MDR is based on the value of each individual UPI transaction. That's why, if a 6000 payment is divided into three distinct payments of 2000 each, every individual transaction remains within the 2000 limit. Consequently, under the current interpretation of the rules, no MDR would be applicable to these three smaller transactions, while this technicality suggests that splitting payments could theoretically save the merchant the 24 fee that would have been incurred on a single 6000 transaction.
Legal and Regulatory Standing of Payment Splitting
Regarding the legality of this practice, reports from Financial Express indicate that there is currently no explicit prohibition in the existing or proposed rules against a customer splitting a large bill into multiple smaller UPI transactions. There is no specific regulation that directly declares the act of making three 2000 payments for a 6000 bill as illegal. However, this doesn't grant customers an absolute right to force merchants into accepting multiple split payments. Merchants maintain the prerogative to insist on a single payment based on their own operational requirements, including accounting practices, refund processes, payment settlement systems, and fraud control measures.
Risks Associated with Frequent Transaction Splitting
While splitting payments might seem like a simple way to avoid costs, it carries several operational and security risks. Making multiple identical payments to the same merchant within a very short timeframe can be flagged by bank security systems as an unusual or suspicious transaction pattern. Such automated flags could lead to temporary transaction blocks or even a suspension of UPI services for the user. On top of that, banks often impose limits on the total number of transactions allowed per day, and splitting every large bill could quickly exhaust these limits, while for the merchant, multiple payments translate into increased administrative work. Tracking and reconciling three separate entries of 2000 is inherently more complex and time-consuming than managing a single entry of 6000.
Merchant Obligations and Customer Rights
A critical aspect of the new UPI MDR regime is that the MDR isn't a charge to be paid by the customer. It's defined as the cost of accepting payments for the merchant. According to guidelines from the government and the National Payments Corporation of India (NPCI), merchants are strictly prohibited from passing this cost on to the customer. If a merchant demands an additional MDR fee from a customer for a UPI payment, the customer has the right to file a formal complaint. That's why, splitting a 6000 bill specifically to avoid MDR isn't a necessity for the customer, as they aren't the ones paying the fee. If a merchant prefers a single payment, the customer should proceed normally, while it's also possible that in the future, the NPCI or banks may introduce specific anti-circumvention rules to address the practice of payment splitting.