
- India,
- 24-Sep-2026 09:11 PM IST


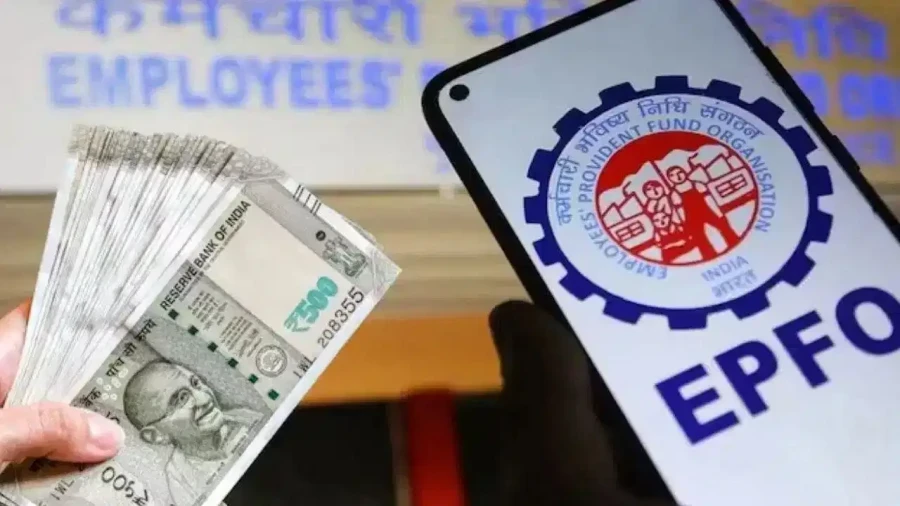
The global financial landscape is currently witnessing significant shifts as the 30 year bond yield in the United States has climbed to its highest level since 2004. This surge in yields, coupled with the rising prices of crude oil and persistent concerns regarding the Federal Reserve's interest rate trajectory, has exerted considerable pressure on the Indian stock market. In such a volatile economic environment, the importance of secure savings like the Employee Provident Fund (EPF) becomes even more pronounced for salaried individuals in India.
Understanding the EPF Scheme 2026 Updates
The Employee Provident Fund is no longer viewed merely as a long term retirement corpus. It has evolved into a versatile financial tool that employees can tap into during times of specific need, while under the newly structured EPF Scheme 2026, the regulations governing partial withdrawals have been Importantly streamlined compared to previous iterations. One of the most prominent features of these updated rules is the provision for housing related expenses, which allows members to take advantage of their accumulated funds for significant life milestones such as buying or building a home.
Eligibility Criteria: The 12 Month Rule
To avail of the withdrawal facility for housing purposes under the revised guidelines, a fundamental eligibility criterion must be met. An employee is required to have a total EPF membership duration of at least 12 months. Once this one year milestone is achieved, the member becomes eligible to apply for funds to facilitate various housing activities. This includes the purchase of a new house, a flat, or even a plot of land. On top of that, the funds can be utilized for the construction of a house on an already owned plot, the repayment of an existing home loan, or for the essential repair and renovation of a current residence.
Withdrawal Limits and the Eligible Member Balance
The most critical shift in the new regulatory framework is how the maximum withdrawal limit is calculated. Previously, limits were often tied to multiples of the employee's salary. However, the new system focuses on the Eligible Member Balance. According to the rules, a member can withdraw up to 100 percent of their Eligible Member Balance for housing needs. However, there is a mandatory retention clause: at least 25 percent of the total balance in the PF account must be maintained for retirement purposes. Effectively, this means that a member can withdraw approximately 75 percent of their available eligible PF balance, ensuring that a portion remains secured for their post retirement years.
Permissible Housing Expenses
The housing category under the EPF withdrawal rules is comprehensive, covering a wide array of financial requirements. Employees can seek partial withdrawal for the following specific purposes: purchasing a ready to move in house or flat, buying a residential plot, constructing a new home from scratch, making principal or interest payments towards a home loan, and carrying out necessary repairs, renovations, or structural improvements to an existing property. It's important to note that this withdrawal facility for housing can be utilized a maximum of 5 times throughout the entire duration of the employee's membership.
Focus on Balance Over Salary Multiples
The transition from salary based limits to balance based limits represents a major structural change, while in the past, the amount one could withdraw was often restricted by how many months of basic salary and dearness allowance they earned. Now, the primary factor is the actual amount present in the PF account. For instance, if a member has an eligible PF balance of 1,000,000 rupees, the requirement to maintain 25 percent means that 250,000 rupees must stay in the account. Consequently, the member could potentially withdraw up to 750,000 rupees. The final approved amount, however, remains subject to the records held by the EPFO and other applicable terms and conditions.
The Necessity of UAN and KYC Compliance
For a easy withdrawal process, it's imperative that the member's Universal Account Number (UAN) is active and all Know Your Customer (KYC) details are accurately updated, while this includes ensuring that bank account information, Aadhaar details, and other personal identifiers are correct in the EPFO database. Any discrepancies in bank details or KYC documentation can lead to the rejection or delay of the claim, while the new system is designed to be more online centric and automated, making accuracy in documentation more vital than ever.
Provisions for Working Couples
The rules also address scenarios where both husband and wife are individual EPF members. If both spouses meet the eligibility criteria, they're both permitted to withdraw funds from their respective PF accounts for housing expenses related to the same property. Each spouse's withdrawal limit will be determined independently based on their individual PF balances and the specific limits applicable to them. This provision provides a significant financial boost to households where both partners are contributing to the provident fund.
Conclusion
The updated EPF rules have made the process of accessing funds for housing much more accessible and transparent. By completing just 12 months of membership, employees can benefit from their savings to secure their housing needs, whether it's buying, building, or repairing a home. While the flexibility is increased, the mandate to keep 25 percent of the balance ensures that the primary goal of the EPF—retirement security—isn't compromised.